Showing posts with label space group. Show all posts

Wednesday, 25 May 2011

What future for our industry?

What does the future hold for our industry?


On the front page of the Financial Times yesterday was an article about the incredible decline in construction output during 2011. Overall construction workload fell by a staggering 39%. This is the most significant fall for the past 35 years. There were turnover statistics from several of the major construction companies, including Kier and Balfour Beatty, which indicated the considerable reduction in their construction turnover in the period.


The quarterly GEP figures issued for Quarter 1 suggested that construction output was down by nearly 5% in the period. There are no regionally adjusted figures so I would anticipate that the decline in the regions is far greater as the overall figure will be bettered by investment in the South East.


This catastrophic level of change in any industry will inevitably reshape the future considerably. For the construction industry, clearly we will never go back to the past and the type of industry it was over the past 15 years will not be seen again. We are in a period of flux at present where there is little workload or revenue, but at the same time there are improvements in technology which could reshape how we design, deliver and operate buildings for the future.


All businesses are keen to set out a vision of sustainability which looks to provide steady employment and profit for those involved in the businesses, something which is clearly under considerable threat in the construction industry at present.


As I look into the future I believe it is impossible to predict where we will be in 2 or 3 years time. Long term investments are a considerable gamble with the future being so unpredictable. Many firms are shrinking their regional presences and looking to develop opportunities in the South, which will obviously drain talent from the regions. Organisations are consolidating and changing on a regular basis. International markets continue to be the lifeline of most organisations that are able to stay afloat.


This generation has never seen such a dramatic downturn, and construction leaders are drawing on much of their experience to maintain business sustainability. While it may be difficult to predict where any of us will be beyond the next 12 months, all we can hope is that when we do see a light at the end of the tunnel, the future will be different, but secure, as well as exciting and challenging. Hopefully we can all learn lessons from this period and ultimately ensure we all have a better future.


Tuesday, 10 May 2011

The big housing question

I have been inspired to write this blog entry following a recent episode of Panorama. The programme was all about the need for affordable housing across the UK. There was a shocking contrast of housing in London which was fraudulently being let by landlords at extortionate rates and a family of 9 in Sheffield living in a 3 bedroom house.


There are around 5 million people on the housing waiting list in the UK and it was clear that the majority of people on this waiting list have no chance of being housed. During the show, Portsmouth Council went through their own list contacting most of the people on it, informing them that there was no chance of them ever being housed by the Authority. This meant that they cut their list considerably.


The big question however, is what happens to the people who will never be housed?


We have been developing Spacehus as a potential product for this market and we have managed to get a 3 bedroom house at an all in cost of around £84k on a small development. The running costs of this house would be around £10 per week which also would go some way to address fuel poverty.


A concept image of the £84k Spacehus that could help solve the affordable housing issue


The challenge is however, encouraging RSLs to develop. I have spent the last few months talking to many RSLs, and there is not ability or desire to develop new homes. This therefore means that the market is stagnant, so as no improvement is being made in relation to the waiting list, we face the problem of it getting longer.


It seems the reasons the RSLs are reluctant to develop is that they have been familiar with the grant process and the Government is now encouraging to change models and progress with an affordable rent model, which seems to increase their risk considerably in the longer term. All the details are not clear at present and I hope that I can dig deeper to understand what the problem is and to try and find a way around the challenges and encourage take up.


It does seem however, that there is a standoff between the Government and Social Landlords, meaning that we have a growing housing crisis in the UK.


Land values continue to be unrealistic and planning continues to be challenging. Both of these are preventing private sector involvement, putting the market in stalemate.


I still remain convinced, with my entrepreneurial hat on, that there is a need for housing which is affordable to buy or rent and run. At _space group we will continue to invest in finding a solution to this problem, until we find a way of getting affordable sustainable homes delivered.


For a number of years, we at _space group we have been driven by the purpose of making life better. After watching Panorama, I am sure that if we manage to crack this problem we will definitely make life better for the family in Sheffield who are currently sleeping on the settee.

Tuesday, 1 March 2011

The Future of Architecture

Will onsite be replaced by offsite manufacture in the future?

The recent publication by Building Futures about the future of architecture is an excellent insight into the challenges facing the industry. The report paints what I believe to be an incredibly accurate and perceptive view of our future.

The premise of the document is that there may be no architecture profession by 2025, which is an interesting argument and one I feel is close to what will be the reality of the situation.

Ultimately, I believe that the RIBA will end up representing two very different types of organisation.

At one end of the spectrum, the RIBA will represent the small general practitioners which operate in local markets on one-off niche projects. At the other end of the spectrum they will represent architects internationally – large international practices which deliver high profile complex schemes around the world.

Those medium-sized architects face the future of a diminishing marketplace. Previously, these practices have been involved in large Government programmes such as BSF or P21+. They have also delivered mixed use commercial schemes for developers across the UK.

In reality, it is no longer an option for these practices to rely on the Government for work, as the marketplace and requirement for these schemes is disappearing fast. Such organisations need an ongoing growth and revenue to provide investment in training and development and to cover large overheads.

The report hints at what these practices need to do to survive. They will need to reposition themselves and do something different in the marketplace.

Their future lies in capitalising in the need for a coordinating role. The use of BIM in construction projects supports the need for a lead designer or coordinator. There is an opportunity to embrace this role however I am sure many design managers within construction businesses will attempt to take on this role for themselves.

The role of consultant engineer may also diminish as both M&E and structural sub contractors take on more and more of the technical requirement.

The medium sized practice could also look to develop products on behalf of the industry. There is an opportunity to use the design skills which architects have to produce buildings which are manufactured rather than constructed. These products can then be sold to the large contactors or direct clients. If the designers can be clever enough they could create products which depend less on constructors and more on assembly, changing the industry through an investment in innovation. Large contractors who have strong balance sheets tend not to invest in research and development and are happy to continue to deliver projects how they have always been delivered.

The final area of opportunity for these mid-range practices is on international work. Over the past 10 years many of these practices have built up a great amount of experience in designing hospitals and schools. These skills should not be wasted and can easily be exported to other parts of the world. It will mean competing on a global stage, but with the right targeted marketing there may be an opportunity to fill the gap left by the reduced spending in the UK.

There is no doubt that the prognosis for architectural practice as we know it today is not good. By 2025, the profession will be very different and many of the current medium sized practices will not exist in their current form. A number of new businesses will have been formed by the more entrepreneurial and innovative business leaders, whilst many of the others will have been absorbed by larger construction companies who have identified the need for the coordination skills which are inherent in the traditional architect.

Thursday, 27 January 2011

It's just the beginning


How far along the road to recovery are we?


Since we returned to work after Christmas I have sensed a notable change in atmosphere and confidence across the industry.


It seems like a number of organisations are making announcements to reduce their costs since they have returned after the break.


I suspect that during 2010 many companies were hanging on, waiting for the market to improve. Unfortunately that has not happened and is unlikely to happen in the near future. I would guess that when the Directors of these companies sat down and looked at cash in the bank and opportunities going forward, some fairly drastic measures had to be taken.


Consultancies would have looked at their costs and realised the only option is to cut resource to minimise outgoings. It is clear, from the fact that there are several small to medium sized construction businesses that have gone into administration since the New Year due to cash pressures and lack of future pipeline, that in some cases, this has not been enough.


I think this process will continue right through 2011 and beyond. I think the last two to three years and the forthcoming two to three years are likely to be the most significant in construction for at least a century. There are many theories of what the impact of this reduction in construction work will be, but I hope that something positive comes out of such a negative situation.


As an industry we can hopefully embrace this period and look to find more efficient ways of delivering buildings to the highest standard.


The Government is putting huge faith in the private sector to drive recovery and with construction being one of the most significant industries in the country, clearly we will all have our part to play in the economic recovery process.

Thursday, 9 December 2010

The Largest Change Management Programme Since Victorian Times

Paul Morrell - Chief Construction Advisor: Image from www.bco.org.uk

Paul Morrell has been at it again. As part of his role for the Department for Business, Innovation and Skills, he has issued a report which has looked at the implications to the construction industry of the low carbon challenge.

His report suggests that the industry faces the largest change management programme since Victorian times if it is to meet the low carbon agenda.

The report came from the Innovation and Growth Team (IGT) which is drawn from the construction industry and is asked by the government to consider how the construction sector could meet the low carbon agenda.

The Climate Change Act requires the UK to reduce its carbon account in 2050 to at least 80% lower than the 1990 base line.

Via the report, Paul Morrell has highlighted some of the good practice which is being carried out throughout the construction industry at present. There are some excellent projects where energy is right at the heart of the project. However, I believe that this is the exception far more than it is the rule.

In the past 12 to 18 months there has been a marked change in the approach to producing energy however, the continually disjointed nature of the process means that it is difficult to deliver efficient results.

Building regulations will continue to become increasingly onerous and our present methods of construction will make it increasingly challenging to achieve these stretching targets.

Over the past 10 years, the industry has proved that, even when there is plenty of work available, it is reluctant to invest in research and development. The industry shoots itself in the foot when times get tough in that it drives cost down without innovation.

Companies such as Laing O’Rourke have invested massively in research and development however, to continue this they need a considerable level of turnover. As part of the report there were some very nice platitudes from some Ministers stating how important the carbon issue would be to the construction industry.

I do not believe the industry will make this investment itself as it is naturally conservative and fearful of change, and the race for growth without investment is very raw to the industry at present following the spectacular demise of Connaught and Rok.

There is no incentive for the construction industry to invest in reducing energy and certainly if there is no commercial benefit to clients they are unlikely to invest themselves.

For us to get the significant improvements we need in energy performance, the Government needs to legislate to achieve these stretching targets. There will be kickback from the industry claiming the targets cannot be achieved however, this pressure will drive the industry to find ways to solve the problems.

Businesses who respond positively should be rewarded by the legislation and those who don’t should be penalised.

Unfortunately I do not have the answers to how this can be carried out but I do know that without it the industry will continue to progress as it always has done, with organisations continuing to undercut each other to win the next project.

Monday, 13 September 2010

Wanted - 100,000 School Places

Students will have to work harder in overcrowded classrooms if changes aren't made - image from _space group.

Recent research has revealed that England is facing an acute shortage in the number of school places, with more than 1 in 10 pupils in the country in schools suffering from overcrowding.

The suggestion is that the government will need to build a total of more than 100,000 places at primary and secondary schools, at a cost of up to £2bn. 50,000 of these places are required just to alleviate overcrowding, while the other 50,000 are places that local government officials have estimated will be needed to prevent the spread of overcrowding.

This overcrowding is driven by attempts by Local Authorities to cope with the lack of good schools in their boundaries. Popular schools are being allowed to grow beyond their buildings’ limits, so that as many families as possible get a place at their first choice institution. This means that already full schools will be unable to expand to meet demand as pupil places continue to rise, and larger shares of children will need to take up places at less successful schools.

Not only could a lack of classrooms force schools to increase class sizes, it also threatens to undermine the government’s plans to boost competition in education, which appears to depend on spare capacity for children to move between schools.

Currently, more than ¾ million children, 12% of the total in Local Authority schools, are in buildings that are more than 4% over the capacity for which they were designed. Among these children, more than 250,000 are in schools that are 10% over the limits of their facilities, while over 60,000 are in schools that have 20% more students than their buildings are intended for.

Considering that the amount of four year olds is set to rise by 8% over the next two years, this issue will only get worse, and in order to prevent overcrowding, Local Authorities will need to find another 25,000 new primary school places, with similar numbers for secondary schools required by 2014/15.

These growth numbers will be problem for a new education secretary who is planning wide-ranging reforms. His reforms are intended to increase the competition among schools. However this relies on a margin of spare capacity and new link choices to be made.

Apparently the school places crunch is not evenly distributed with London suffering particularly badly. The previous government had identified indentified investment for Local Authorities facing the shortage of primary school places and Building Schools for the Future was intended to be the long term answer to this issue.

Obviously, there was a bit of political too-ing and fro-ing on this issue, however there can be no doubt that the overcrowding is increasing and that this is likely to be a political timebomb. Clearly, there needs to be a stand back in relation to education building provision and how this aligns with ambitions, policy and performance of schools.
Rob

Tuesday, 31 August 2010

The New Homeless

It is becoming increasingly apparent to me that we have a generation of new homeless people – young people in their 20s and 30s.

Actually, homeless may be too strong a word for them, and more appropriate is ‘houseless’.

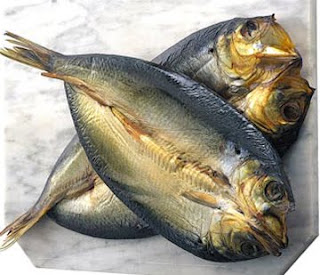
This generation are either finding it very difficult to raise the funds to buy a property or have seen the down side of taking large loans and do not wish to get a foot on the property ladder. They even have their own term – KIPPERS, or Kids in parents’ pockets.


"KIPPERS" - it doesn't just refer to a fish


I seem to come across an increasing number of young people who in this situation, still living at home with their parents and desperate to move into a place of their own. Many of these young people have not saved money because this has not been something that they felt they needed to do in the times of excess. Now they need deposits of 20-25% to get a mortgage and their ability to raise this level of cash is difficult.

At _space group we have quite a few of our team within this age bracket and I am aware of a significant number of our people who are still at home with their parents, some in relationships finding it difficult to build a future together. There are even some who are starting families and still remain in separate properties.


The "KIPPERS" are ready to leave home, but can't get on the property market

Because of the need for such a large deposit, the private rental market has become attractive to a lot of KIPPERS, even though the products on the market are not great. At one end you have low quality, bedsit-type accommodation, and at the other, expensive riverside apartments. It is the more pragmatic accommodation in the middle which we seem to be without.

I know some RSLs have identified this and are trying to feed the market, but they themselves are suffering from funding challenges. I know recently of an RSL that put such properties on the market and there were huge waiting lists from people wanting the opportunity to rent, so it is clear that the demand is out there.


At _space group, we have developed a low cost house for the social housing market within our _spacehus brand. This is within the affordable window and also has minimal running costs. We have achieved this through offsite manufacture, which has allowed us to give each hus the highest quality in airtightness and insulation.


We are currently working on producing a £99,000 house, with running costs of £10 per week. While our buildings have low energy credentials, there is something else driving the project that we think is very important – by keeping the running costs low, the money the homeowner saves can be put towards paying the mortgage.


Our plan on the £99,000 house is to work on a 15% deposit with an 85% mortgage.


We are hoping to find a funder who will work with us who will help a whole generation own a home.


These £99,000 houses would even be appropriate for market rent if we can buy land at a realistic price. In the meantime, watch this _space!


Rob.

Friday, 2 October 2009

Classroom of the future

A 3D of our TES 'Classroom of the Future'

I'm on way down to the TES (Times Education supplement) exhibition in Olympia in London today. This is a 2 day gather of a wide range of the teaching profession. We are showcasing learnspace which is our classroom of the future. We have a 65 sqm space which we have set up as a space which could be the classroom of the future.

We believe spaces need to be flexible, adaptable and diverse to suit a whole range of learning approaches. We have an IT partner who is showcasing the latest technology. We will have everything from large format screens for sharing information to itouch for personal information.

We have a couple of furniture partners who range from the specialist fixed furniture through to loose furniture. Ergonomics are forgotten in a learn space and need to be given more consideration in the future. This should be an exciting couple of days.

Tuesday, 1 September 2009

A Spot of Holiday Reading


After my adventures in Florida at the beginning of the summer, I quickly found myself in need of another holiday.

We have just returned from a trip to Madeira - a beautiful island and the home of Ronaldo!

As ever, my holidays give me the opportunity to catch up on my reading. My taste in reading materials are a little ‘anorak-ish’ but I thought I would try my hand at reviewing some of the books I read whilst I was away, as I don’t have much more to report on because I didn’t get much further than the swimming pool!

Leading from the Front: My Story. Gerald Ronson

The first book I read was the story of Gerald Ronson who heads up the Ronson Group, which was a very successful business in the 70s and 80s. It ran petrol stations whilst more recently the group has become an international property developer.

Gerald Ronson is now aged 74 and is still working a 6-day week! His story is fascinating and takes you through how he grew a business, lost it all, and then grew it back again. He was infamously involved in the Guinness shares trial and ultimately ended up spending time in prison. He gives an interesting account of his life, how he shaped his future and what is important to him.

His family and community are a large part of his life and he has spent much of his time supporting Jewish charities over his 60 years in business. He is so matter of fact about the people he has met, from royalty to celebrities, many of whom became his friends. His company crashed in the last recession and after some poor investments in America, he was forced to sell large parts of his equity.

He continues to run the business on a day-to-day basis and is now the grandfather of property development in the UK - seen it all and done it all.

This was a fantastic read especially with the focus on development and the economy. Clearly, Gerald Ronson puts his family and his community at the top of his priority list and he clearly demonstrates how you can have success yet still share with others.

Common Sense Rules. Deborah Meaden

Out of the current five dragons on Dragons Den, four of them have written autobiographies. I have now read all four after reading the recently published, book by Deborah Meaden.
This is a fairly light business book giving common sense examples of how to run a business, as well as examples of how Deborah Meaden grew her organisation and ultimately sold it to venture capitalists.

Much of the information is common sense but still useful by giving a brief insight to the author who is clearly an effective and focussed business manager. This is a quick read targeted at those who watch Dragons Den.

Friday, 24 July 2009

Investing in Standards During a Recession


Going back to the 80s I was one of the greatest critics of the BS5750 and the Quality Assurance process. I remember wading through huge documents and ticking thousands of boxes just to be able to demonstrate we had carried out everything in accordance with our procedure. The reason for my criticism was that I was not convinced that this delivered any real value to the business.

However, over a number of years the standards have been reviewed and have been changed to ISO 9001 which used the Demming plan, do, check, act model.

We spent a lot of time as a business reviewing ISO 9001 and decided to develop our own continuous improvement wheel based on plan, do, check, act. We used the 9001 standard as a base however. I remember in the past when we had a QA audit there was two weeks of frantic activity before the Auditor arrived to make sure that every box was ticked and every piece of paper was in the right place. Now we look forward to the auditor arriving and make no special arrangements for these particular days. We use the audit as opportunity for continuous improvement.

We have named out internal management system _scils (_space Continuous Improvement and Learning System) and have been able to integrate other standards within it without major change.

We have recently been accredited with ISO 14001 in relation to environmental standards. Far from believing that quality standards are a hindrance I have now moved my thinking to believe that such standards are imperative in time of recession. Particularly with ISO 14001 it has structured our thinking in relation to waste and risk. We now look at every aspect of the business and consider where waste is being produced and how we can minimise it. By measuring what we use in the first place we can monitor resource movements and percentages against others.

We are now aiming to include the ISO 18001 standard within our _scils model to ensure that our Health and Safety achieves the highest standards.

During a recession when process, waste and risk are very important I would recommend any business to invest in these standards to ensure that the organisation is run as efficiently and effectively as possible as I believe they add real value.

Saturday, 18 July 2009

The Big Four O

Life begins at 40... / photo

I reached a major milestone at the weekend. On the 11th July I hit the grand old age of 40. Some say life begins at 40 and I look forward to what that may bring. I have to be honest usually birthdays have little impact upon me however, I got to thinking that if 80 is a good innings, by the time you get to 40 you are half way there meaning that its all down hill from here!

My 30ies were an exciting time for me and this period generally coincided with the last 10 years of growth. Whilst growth was very exciting it provided its own challenges and headaches.

It is likely that my 40ies will have a different set of challenges as we steer the business through a difficult period.

For the man who has everything birthday presents were always going to be a challenge. The best present was the party which I had last Saturday night. These are rare occasions where all of your friends are gathered together in one place at the same time. Obviously one is your wedding providing you only have one and the other is likely to be your funeral which you won’t be at.

The one thing that struck me on the evening was that friendships are recession proof and in my case I have been fortunate enough to have a solid bunch of friends through the ups and downs over the years.

Friday, 17 July 2009

Batten Down the Hatches

Over recent months one of the terms which I keep hearing in our industry and in particular from architects is that they plan to ‘batten down the hatches’ and ‘ride out the storm’. I think in the past this has been the way many architectural businesses have responded to recessions and generally the profession is badly hit by such down turns. Much of this is caused by the fact architects depend upon capital spending and in recessions this is one of the first things to be cut.

Over the past decade our industry has made huge strides forwards in relation to its approach and technology. There is no doubt that there is still further to go but my worry is that much of the hard work we have done in relation to partnering or integrated working will be stopped and potentially be forgotten.

As an industry we need to continue to invest in training and development.. With Building Information Modelling and integrated project delivery we are on the cusp of a revolution. Unfortunately many companies are battening down the hatches and cannot afford to invest.

I also worry that by battening down the hatches the storm will happen around us and when many companies open the hatches there will be no industry left.

At _space we made the decision to think very carefully about how we move forward but do not intend to batten down the hatches or bury our heads in the sand. We will continue to invest in our people and technology and think differently about our industry.

Hopefully this will stand us in good stead for the future and in fact help us weather the storm.

We are always looking at how we can diversify our offer to enable us to sustain our business for the long term.

Monday, 6 July 2009

An Old New Town

Milton Keynes/Wikipedia

I spent sometime in Milton Keynes last week, this was the first time I had had the privilege of visiting this much talked about town.

My first challenge was getting there, as a regular train traveller cutting across country was going to be problematic. The answer was to head into London and back out to Milton Keynes. I was on a secret mission and the first thing that struck me on that particular day was the incredible heat with temperatures reaching 32 degrees.


At _space we talk much about sustainable communities and I am always looking for the collective elements that can make this happen. Clearly, at some point, Milton Keynes was thought to be state of the art. Many years later the masterplan has been developed and the new community created.

What I am not sure about is, if this is an integrated or sustainable community. It has all of the pieces but many of the elements operate in isolation. It has to be economically sustainable in that it is operated for several years and continues to grow. However the roundabouts and road system gave little priority for pedestrians with huge industrial zones being surrounded by forests of trees.

The housing seemed to be remote lacking the usual mix of a buildings and styles developed over many years.


Much of the architecture was of a similar 60ies and 70ies style again with little response to human scale.


It would seem from the outside that commercially Milton Keynes has been successful, possibly due to its good links to London by both road and rail. I would challenge however, whether this is the best place to live if there is the rich mix of uses, ages and architecture which can create a place.

I came away from Milton Keynes believing that it was difficult to force a community to happen on a rigid plan such as this. Communities need to evolve over time and respond to the times in which they develop.

Places also need to be particular to their geography and I did feel that whilst I thought I had not been to Milton Keynes before I had visited the same place in Telford and Washington.

Friday, 26 June 2009

North-South Divide

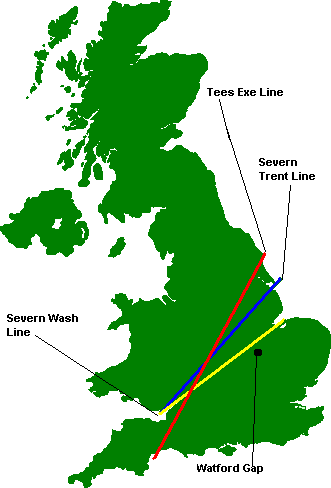
North-South Divide map/Wikipedia

The recession is starting to have quite a cultural impact on the architectural profession. My view has always been that in architecture there has been a London market and a regional market. Much of what has been delivered in the capital has been commercial responding to the asset boom driven by the banks. This has included offices, hotels and high end housing.

The majority of the construction industry is now driven by Government spending and investment in education and healthcare. This has encouraged many of the businesses in London to look further afield for opportunities.


The concentration of skills in London will help to increase the quality of public buildings being procured across England.


With regards to the upgrading of the of the schools estate, Partnerships for Schools are now very reliant on CABE as the custodian of design quality. Over the last few years the BSF process has been driven by delivery and the procurement itself. CABE’s involvement will undoubtedly raise standards and encourage bid teams to respond to the need for design quality.

This shift will give the opportunity to promote the benefit of the investment in design as part of the huge capital investment being made by the Government. As a northern business we must ensure we are part of the dialogue with bodies such as CABE and the RIBA which are traditionally based in the south.